Saving for Your Children: A Joint Piggy Bank That Lasts
Building a financial cushion for your children calls for decisions made with an 18-year horizon. An account for when they turn 18, an index fund in their name, or a classic piggy bank: how to decide, how much to put in, and why not to give up halfway.

The mistake almost every parent makes in the first year
The first child is born and, within a few weeks, someone raises the idea: "we should start saving something for them". The intention is good, the timing too, but the execution tends to be disastrous. The usual move is to open a children's savings account the following month, deposit a hundred euros and forget about it. Four years later, the account holds four thousand eight hundred euros, has earned practically nothing, and on reviewing it seriously for the first time you discover that inflation has eaten around twenty percent of its real value. You've saved, yes, but you've saved badly.
The problem isn't the amount, which in many households is the best you can do at the start. The problem is the lack of a strategy. Saving for your children with an eighteen-year horizon is nothing like saving for a holiday or a car. It's such a long horizon that the decisions you make in the first three or four years matter more than the ones you make in the following ten. And yet it's almost always decided in the heat of the moment, without having read three lines about taxation or about the effect of compound interest.
Why the children's savings account solves nothing
The children's savings accounts many institutions offer are, essentially, current accounts with a friendly name and an interest rate that in recent years has hovered between zero and two percent gross. That, in an inflation scenario of between two and five percent like the one we've lived through in recent years, means that every year the money sits still it loses purchasing power. If you deposit a hundred euros a month for eighteen years, at the end of the run you have around twenty-one thousand six hundred euros nominally, but its real purchasing power, in today's euros, is notably lower.
The second reason that account doesn't work is that it's designed for withdrawals, not for accumulation. That is, it's built so you can put in and take out easily, not so the money grows. Long-term savings products need a different architecture: vehicles that harness compound interest, light friction so they don't get emptied on a whim, and clear ownership from the start.
Three possible vehicles and when each one fits
1. An account for when they turn eighteen, in the child's name
The most institutional option. You open an account in the minor's name, with the parents as legal representatives, and you make a fixed monthly transfer. The virtue is that the money, legally, already belongs to the child from day one, which has tax and practical implications: when they come of age, they access it automatically. The drawback is that this same virtue can become a problem if you haven't prepared the young person to handle a meaningful amount at eighteen. Some families, aware of this, open the account but privately agree on more gradual access.
A numerical example: a hundred euros a month for eighteen years in a non-interest-bearing account leaves twenty-one thousand six hundred euros nominally. That amount, received all at once at eighteen, can pay a university tuition, a deposit on a rental, or vanish in six months, depending on the family context.
2. An index fund or fund portfolio in the child's or the parent's name
The most efficient vehicle from a financial standpoint, also the one that requires the most thought. A global index fund at a reasonable cost, with automated monthly contributions over eighteen years, is statistically the tool that best turns saving into wealth. The historic annualised return of global indices, over long horizons, has hovered between five and seven percent real, after inflation. A hundred euros a month for eighteen years at an average return of five percent real becomes around thirty-five thousand euros in today's terms, against the twenty-one thousand six hundred of the savings account.
The key decision is in whose name the fund goes. In the minor's name implies extra paperwork and automatic withdrawal at eighteen. In the parents' name gives more control, but means the money forms part of the adult's taxable assets throughout the period. Each family has to decide according to its context, ideally with an adviser who knows the wealth law in force.
3. A classic complementary piggy bank
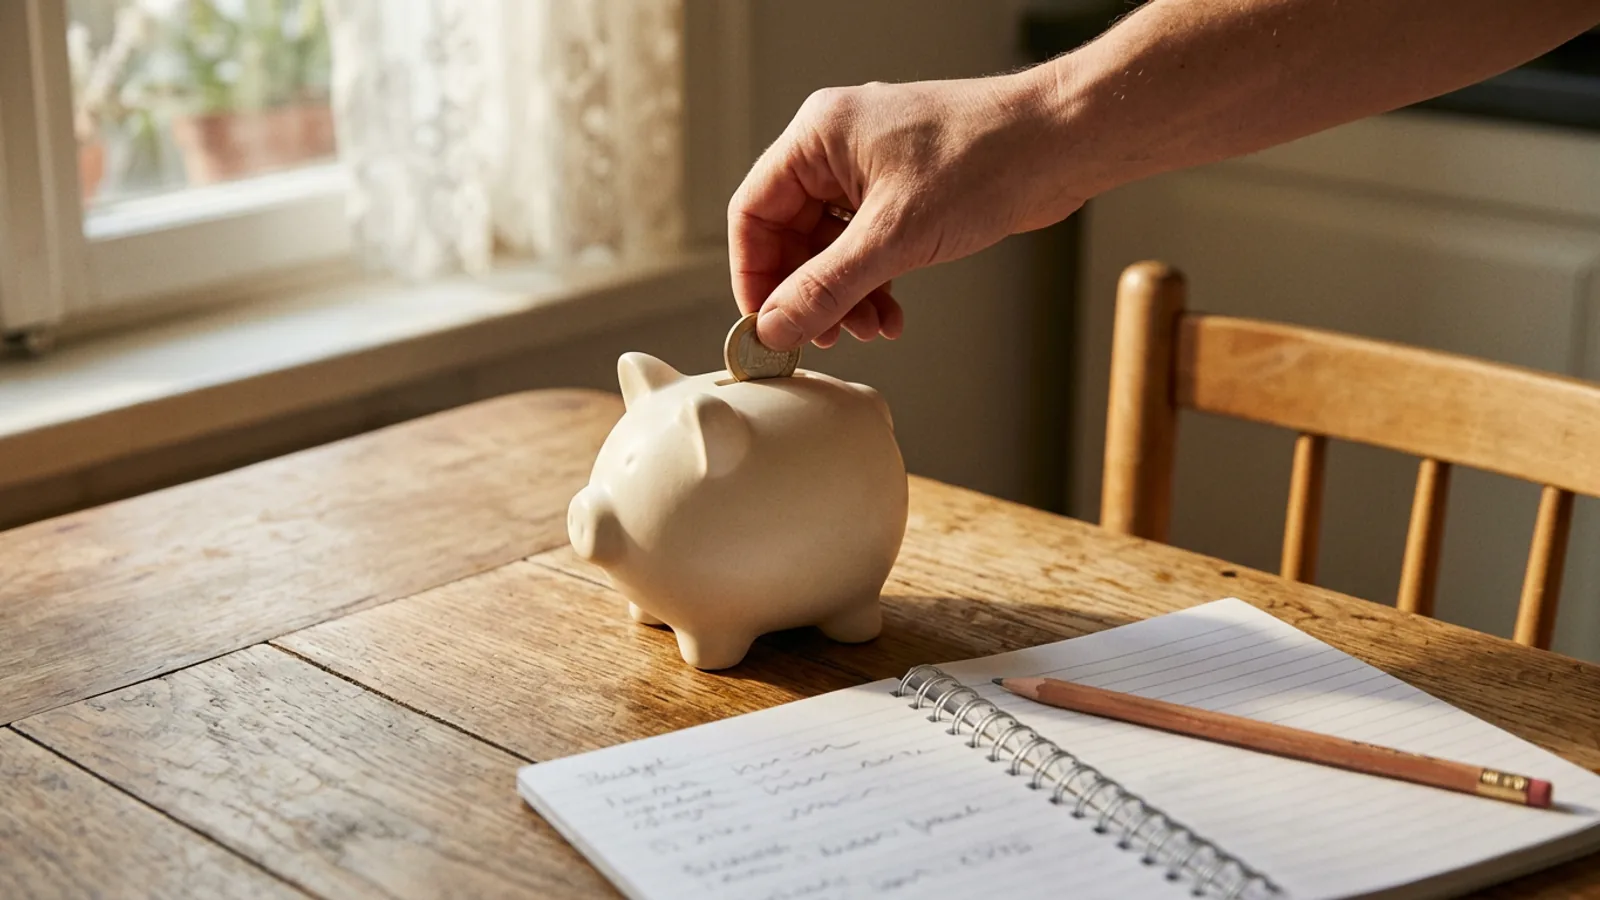
The physical piggy bank, the ceramic one shaped like a pig or an opaque jar, still has a teaching role that shouldn't be dismissed. It's no use for accumulating meaningful capital, but it's useful for the child to learn, from an early age, to see saving as a visible practice. It works as a complement, not as the main vehicle. Thirty euros a month in a piggy bank that's emptied at short milestones, twice a year, teaches the mechanics of saving better than any app.
The problem of not giving up halfway
The hardest part of saving over eighteen years isn't choosing the vehicle, it's not abandoning it. The unofficial but solid statistic in this area says that most children's savings plans are interrupted between the fifth and the seventh year, almost always because a serious unexpected family event has come up. The mortgage goes up, one of you changes jobs, a necessary renovation arises. And then the plan, which was going well, gets paused. And many pauses are never reactivated.
The only way to reduce that probability is to build the plan with two cushions: the child's savings and the family emergency fund. If the second doesn't exist, the first will end up cannibalised at the first serious scare. If the second exists and covers three to six months of expenses, the child's savings can work as a genuinely untouchable account, not as a promise that breaks at the first friction.
How to manage it with four hands without friction
In a couple with a single child, the savings for the minor usually come out of a shared pot fed by both. The contribution can be proportional to each one's income, which is the most reasonable when salaries are lopsided, or strictly equal. In both cases, the plan's success depends on two things: that the transfer is on direct debit and automated, and that both members of the couple have visibility over what's been contributed and what's accumulated.
Visibility is what's most neglected and what generates the most friction in the long run. If one of you handles the day-to-day and the other "trusts" but doesn't look, by year seven the conversation about how the plan is going turns uncomfortable. Any decent system should give you three things: automatic logging of the contribution, an accumulated total visible to both, and the ability to review the history without wrestling with a bank statement. ControlarGastos does exactly that for the household's shared expenses and distributes the cents by largest remainder, not by truncation, so that no one always pays the rounding. For the investment itself you'll also need a broker or an automated manager, but you can keep the visibility of the contributions in the same family ledger.
Conclusion: the gift isn't the money, it's the habit
Parents who reach their child's eighteenth birthday with a significant amount have done two things right. The first is having chosen a reasonable vehicle. The second, far more important, is having built up over eighteen years the habit of treating that saving as sacred. That second part is the one that almost always fails, and the one no financial product can do for you.
What the young person receives at eighteen isn't just the balance. It's also the documented proof that their parents held to a decision for almost two decades without breaking it. That proof, intangible, is worth as much as the money. And, paradoxically, it's only built by doing small, fixed, boring things over a long time. Which is, almost always, the real definition of serious financial work.
Keep reading
Blended family expenses: children from past relationships
Children from the first marriage, children from the new partner. Child support going out, child support coming in, child-specific expenses and shared ones. The arithmetic of affection in blended families demands clarity before generosity.
School Supplies: The Most Expensive Day of the Summer
In the last week of August, a family with two primary-school children can drop three hundred and fifty euros in a single afternoon. It's not bad luck: it's a predictable expense worth breaking down piece by piece so it neither frightens you nor knocks September off balance.
Kids' clothing: the real cost and how to split it
Little ones' sizes last three or six months, garments wear out before they're worn out and the wardrobe is a bottomless pit. Looking at the real annual cost helps you budget better and split it sensibly between both parents.
Sound familiar?
ControlarGastos automates splitting expenses with your partner, flatmates and friends. Split to the cent, no arguments.
Start for free